Click to Enlarge
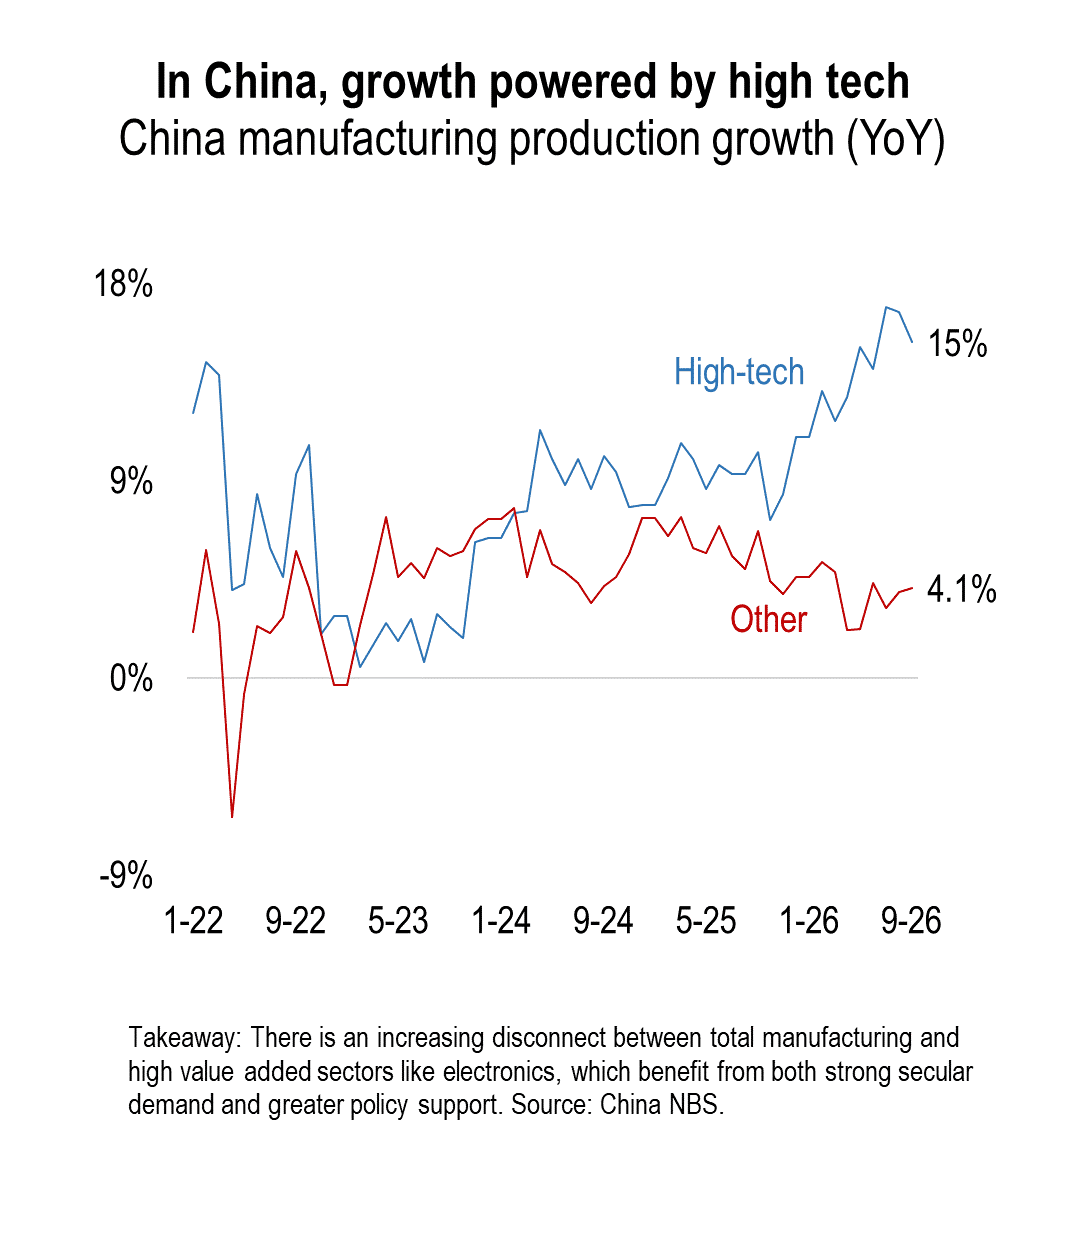
China’s economy grew 4.5% year-on-year in Q3, up from 4.3% in Q2 and slightly above market expectations. Strong exports and high-tech manufacturing continued to stand out as the pillars of the acceleration, while household consumption and property investment remain subdued. Today’s chart shows how this uneven performance extends to the industrial sector. High-tech manufacturing continues to significantly outperform the rest of the industrial sector, with the gap between the two widening significantly YTD. This divergence highlights how China’s industrial expansion is increasingly concentrated in high-value-added industries, even as weak domestic demand continues to weigh on more traditional producers. Why this matters: China’s economy is increasingly K-shaped, with high-tech manufacturing supporting growth while domestic demand remains weak. Although we see a high probability that GDP growth exceeds Beijing’s 4.5% target for 2026, sustaining this momentum will be difficult without a broader recovery in household consumption and investment.