Click to Enlarge
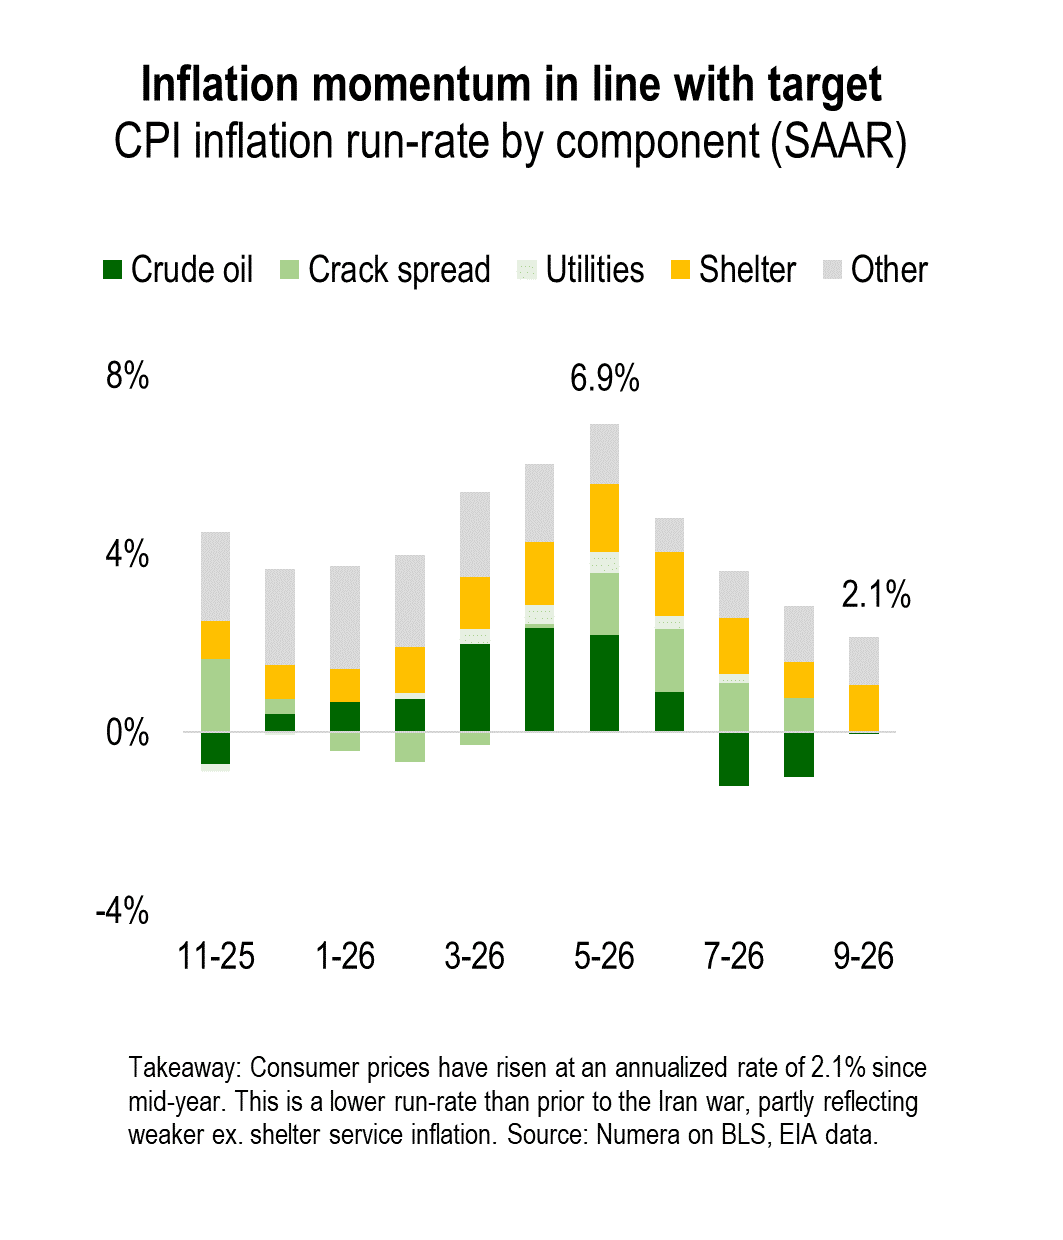
The Bureau of Labor Statistics (BLS) reported that headline inflation accelerated to 3.7% year-over-year in September, slightly exceeding market expectations in light of rising energy prices. In addition, markets expected inflation to broaden beyond energy, with core inflation also coming in hotter than expected at 2.6% YoY. Today’s chart breaks down the contribution of key categories to CPI momentum (4-month moving average). While the crack spread (a measure of refinery margins) stabilized and crude oil prices increased, there is little evidence of widespread pass-through to a wide array of prices. Outside energy, inflation is running at a 2.1% annualized pace since mid-year, largely in line with the Federal Reserve’s 2% target. With oil prices remaining above $100 / barrel for a protracted period, markets continue to price in further rate hikes, expecting four more by mid-2027. We believe that the market is misreading the Fed’s hawkish rhetoric. Typically, the Fed pivots when accelerating core inflation coincides with a strong labour market, yet today’s data is not particularly convincing in this regard.