Click to Enlarge
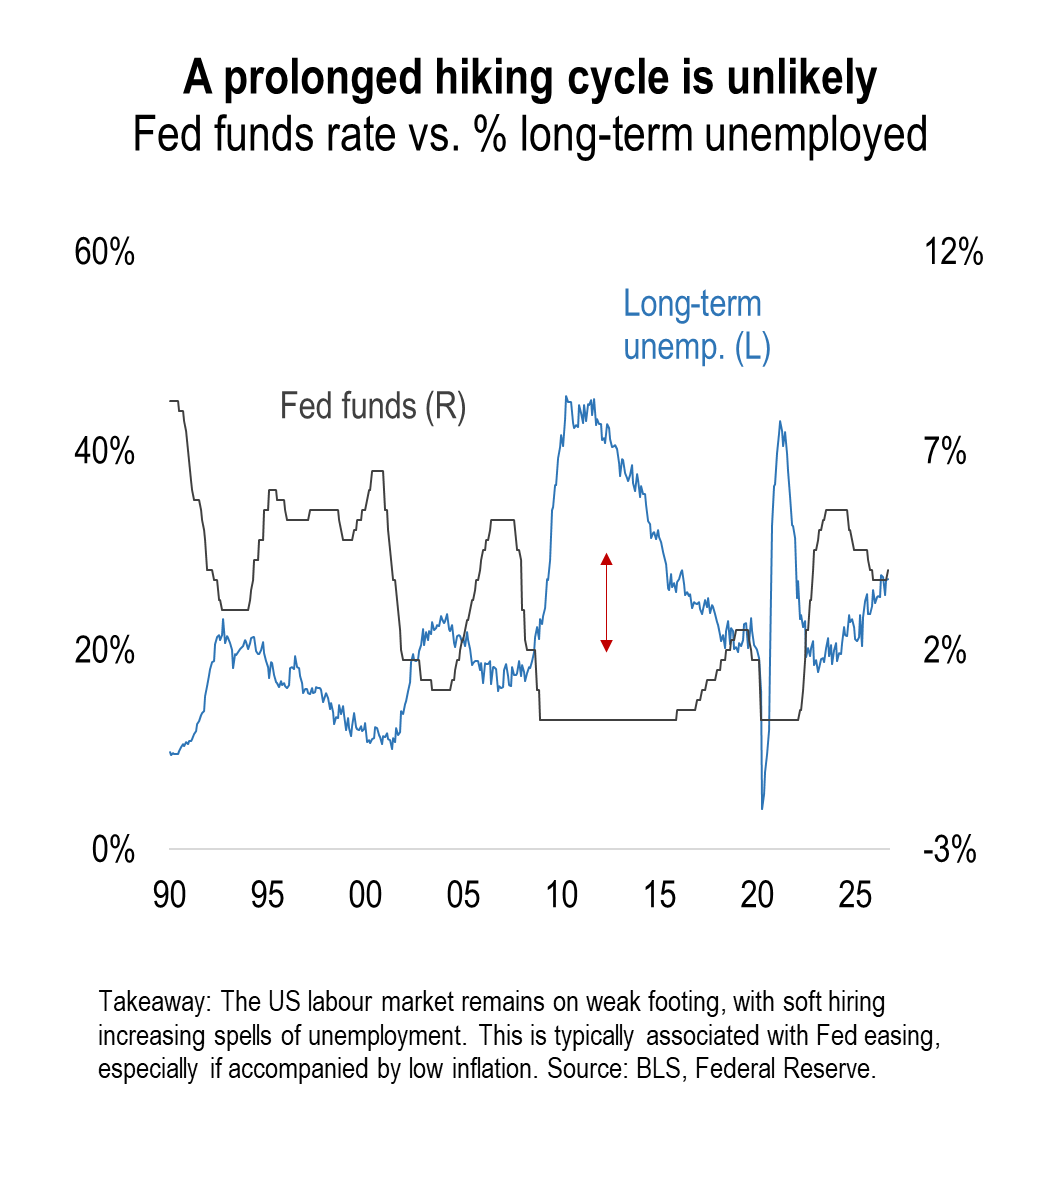
The Federal Open Market Committee is widely expected to leave rates unchanged at today’s meeting, but markets anticipate further tightening ahead. Markets price a 90% probability of a hold ahead of the 2pm ET decision, alongside a 75% chance of a hike by December and three increases over the next 12 months. The FOMC’s recent communication has reinforced this hawkish outlook, placing greater weight on inflation risk than on labour market slack. But as today’s chart shows, rising long-term unemployment and moderating wage growth suggest that labour market pressures are easing. This supports our view that markets are too hawkish on the Fed’s policy path. Even with Warsh’s Fed placing less weight on full employment, softening wage growth should keep the economy from overheating. Why this matters: A less restrictive Fed would ease financing conditions, supporting investment and consumer spending, particularly in rate-sensitive sectors such as housing and durable goods. However, persistent inflation could delay rate cuts, keeping borrowing costs elevated and business uncertainty high.